
You notice that on many high streets in parts of England, where once a bank would have occupied a prominent position, there are now betting shops. More are situated nearby and on the corner of the next cross road. The usual reasons are given for their popularity – high demand from poor customers who are drawn to them because they offer hope of a big return when all else seems lost and companies are willing to take the other side of the bet. For around 40 years, a second reason why such clusters of shops sprang up and were beyond the control of local councils was written into planning law, in a document that few people outside a town hall had ever read.
The Filing System That Runs Every High Street
There are “use classes” for buildings under the planning regime. These are groups of types of use, and if you change to a use within the same class as now you can do so without application for planning permission to change use; a change to a different class needs it.
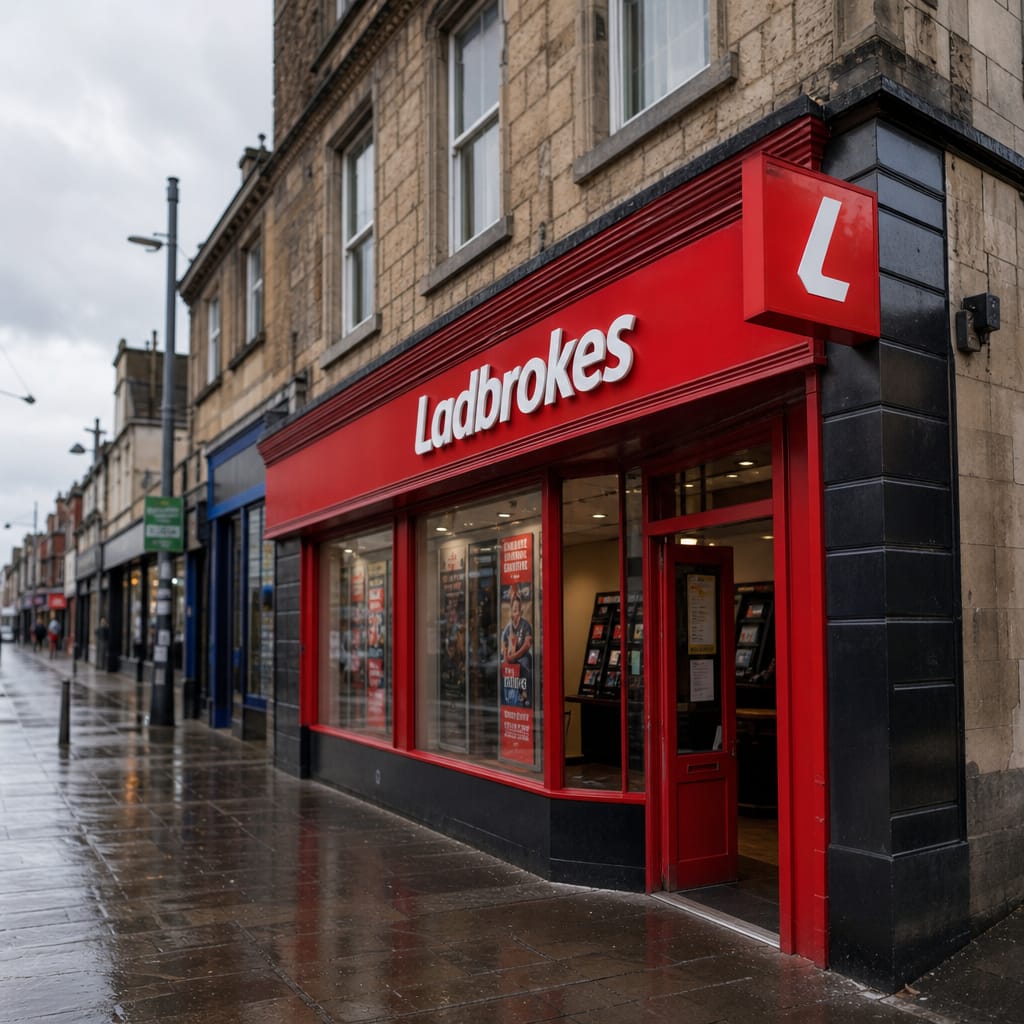
For instance, A2, “financial and professional services”, covers banks, building societies, estate agents and betting shops. Thus, according to planning law, a bank, a building society, an estate agent’s and a betting shop are all the same. So a council would have no more success in trying to stop a fourth Ladbrokes opening on a parade of shops than they would a fourth NatWest branch. The use class is treating them as if they were roughly equivalent. Quite something.
What This Looks Like From the Budget End
A2 units in more affluent areas of the country were taken up by mortgage advisers and solicitors, whereas in poorer areas of the country where such services were not commercially viable, they were taken up by bookmakers. Both were legal and A2. The planning system could not differentiate between them and as a result the provision of financial services in local areas had been partly determined by a use class written by a civil servant in the 1980s.
See The Agreed-Upon Lie That Keeps the Lights On for more on how financial environments affect spending decisions.
2019 and the Lonely Category
In 2019 betting shops were classified as sui generis. This is Latin for ‘of its own kind’. The key point is that a sui generis use is not of a description that can be transferred from one use class to another without planning permission on a change of use. The classification of betting shops as sui generis has therefore handed councils a formal means of objecting to such changes, a legal basis for refusal as opposed to merely expressing concern.
Why a Bureaucratic Category Is a Budgeting Story
Budgeting is not just about discipline and spreadsheets. The environment around us also has an impact on how we behave on a daily basis. What is available and open to us as we walk to the bus stop, what is normalised in our local area, our postcode, all have an impact on us and can have a compounding effect over the years. The high street built around bookmakers and payday lenders is not just down to the choices of residents; it is also partly a result of the planning category that has gone unchallenged for four decades.
Frequently asked questions
What exactly is "sui generis" in planning terms?
A sui generis use is one that does not fit into any of the standard use classes. Examples of such uses are nightclubs, cinemas and launderettes. Because such uses are outside of all the use classes, they cannot change use without planning permission. Every new betting shop is now required to go for planning permission individually.
Did councils actually use the power once they had it?
Some have been quick to react, with several London boroughs already using the reclassification to designate areas where new betting shops will be refused as a matter of policy. Others are taking a bit longer, with whether they pick it up depending on local political will to use the reclassification and the content of their existing planning documents.
Does this clustering problem exist with payday lenders too?
Lenders who operated physical shops were typically classified as A1 (retail) rather than A2, and thus operated under slightly different rules. Their clustering in areas of lower prosperity was similarly determined, though. Subsequent online lending has however transformed the model considerably – a lender no longer needs a shopfront the way a bookmaker does – but the principle holds.
Can residents push a council to act on this?
Yes, through planning consultations and by engaging with the local plan review – local plans are revised periodically and set the policies councils apply when deciding applications. If you want restrictions on certain uses in your area, that review is when residents' submissions actually carry weight.